On 3 November 2026 the Reserve Bank lifted the cash rate by 0.25 percentage points to 4.85%. It was the fifth rise of the year, and the board was split six votes to three. Lenders are passing the increase on, so many variable-rate borrowers will see repayments go up again.
The RBA says inflation is “broadly based” and isn’t expected to get back to the top of its 2–3% target until late 2027. It hasn’t promised that this is the last rise.
If repayments are getting tight
Before you think about selling, it’s worth talking to:
- Your lender or a mortgage broker about refinancing, fixing part of the loan, or extending the term
- Your lender’s hardship team early, if you’re worried about falling behind. It’s much easier to sort out before a payment is missed.
Selling isn’t the only answer, but for some people it’s the right one.
When downsizing makes sense
We see downsizing work well for people who:
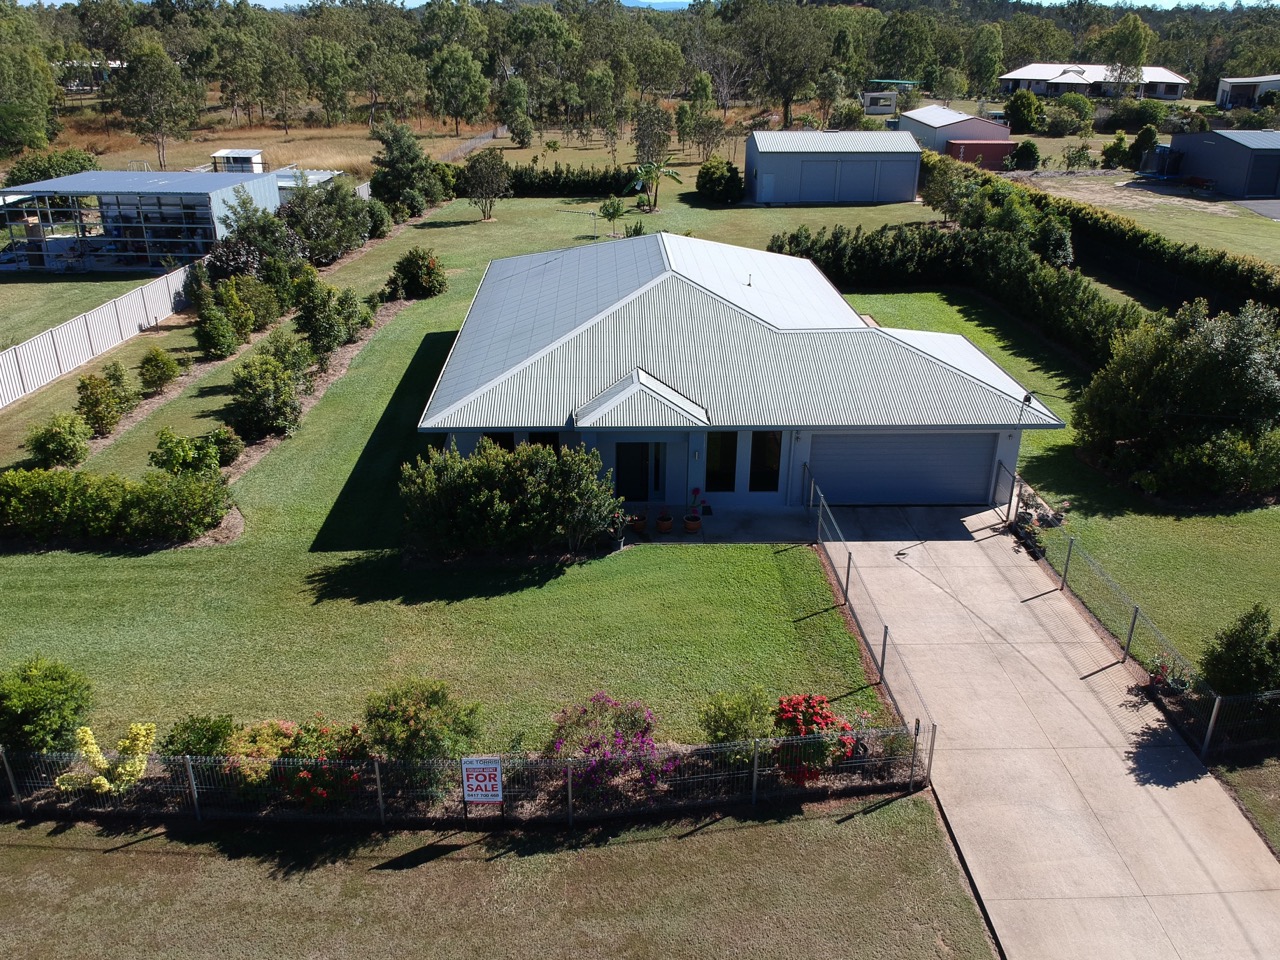
- have a bigger home or acreage they no longer need, now the kids have left
- want to pay off the mortgage, or most of it, and stop worrying about rates
- are tired of maintaining a big block, a pool or a long driveway
- want to be closer to the shops, the hospital and family
Mareeba’s market has grown strongly over the past five years, so many long-term owners are sitting on more equity than they realise. Selling a larger home and buying something smaller in town can free up a good amount of that.
The downsizer super contribution
If you’re 55 or older and have owned your home for at least 10 years, you may be able to put up to $300,000 per person from the sale into your super as a “downsizer contribution”, outside the normal caps. There are conditions, so check with the ATO or your financial adviser before relying on it.
What’s available to downsize into
In Mareeba that usually means a low-set home or unit close to town, a newer home in one of the estates, or a retirement community. New stages at estates like The Rise are also adding lots on the edge of town.
Have a chat first
We’re not financial advisers, so talk to your accountant or adviser about the money side. What we can do is tell you what your home would sell for in today’s market and what you’d pay for the kind of place you want to move into. That gives you real numbers to plan with.
Call Joe or send us a message to arrange an appraisal.